

Personal Loan for Debt Consolidation: Can One Loan Simplify Multiple EMIs?
Having more than one loan can get quite hectic. One EMI is due this week, another next week, and a credit-card payment awaits in the middle of the two. It gets difficult for students, first-jobbers, salaried individuals, freelancers and self-employed to keep track of multiple repayments.
A debt consolidation loan may help make debt management a lot easier here.
Borrowers can take out a new personal loan for debts that they are eligible for and pay all debts with a single loan and repayment plan. However, there is a golden rule to keep in mind: a lower EMI may not necessarily result in a lower overall cost.
Prior to deciding on the consolidation loans, compare the interest rate, APR, processing fee, tenure, foreclosure charges and the overall repayment amount.
Quick Answer: What Is a Debt Consolidation Loan?
A debt consolidation loan is a new loan used to combine multiple existing debts into one repayment arrangement. Instead of tracking several EMIs or payment dates, you manage one loan and one repayment schedule. Whether it saves money depends on the new loan's total cost, tenure and applicable charges.
How Does Debt Consolidation Work?
The process is easier when you break it into five steps:
-
List your existing debts
Note every outstanding balance, EMI, interest rate and due date. -
Calculate your total monthly debt
Add all current EMIs and minimum payments. -
Calculate the amount you actually need
Avoid borrowing more than necessary. -
Compare debt consolidation loans
Check interest, APR, processing fees, tenure and foreclosure terms. -
Repay the existing debts and manage the new EMI
The objective is to simplify your repayment—not create additional debt.
Example
Suppose you have:
|
Existing Debt |
Outstanding |
Monthly Payment |
|
Credit-card dues |
₹15,000 |
₹3,000 |
|
Personal loan |
₹25,000 |
₹3,500 |
|
Short-term borrowing |
₹10,000 |
₹2,000 |
|
Total |
₹50,000 |
₹8,500 |
A borrower may explore whether one suitable personal loan can replace these obligations.
However, always calculate the total repayment, not just the new EMI.
Debt Consolidation Loan Eligibility in India
There is no single eligibility rule for every lender offering debt consolidation loans in India. Requirements depend on the lender and loan product.
Common factors include:
-
Age
-
Income or regular source of income
-
Employment/business profile
-
Existing financial obligations
-
KYC information
-
Banking information
-
Repayment capacity
-
Credit history, where applicable
For example, Pocketly's age range is 18–40 years and lists personal details, Aadhaar-based address proof, verified email, Video KYC and PAN information among its requirements.
How Do I Get a Debt Consolidation Loan?
If you're searching "how do I get a debt consolidation loan" or "how can I get a debt consolidation loan," follow this checklist:
7-Step Borrower Checklist
-
Check the interest rate on every existing loan.
-
Check foreclosure or prepayment charges.
-
Compare suitable consolidation loans.
-
Read the loan agreement and applicable charges.
-
Borrow only an amount you can comfortably repay.
Pro tip: Don't choose a loan simply because its EMI looks smaller. A longer tenure can reduce monthly payments while increasing the total interest paid.
Online Debt Consolidation Loans: What Should You Check?
The convenience of online debt consolidation loans can be useful, but speed should never replace due diligence.
Before applying, check these eight items:
|
Check |
Why It Matters |
|
Interest rate |
Determines borrowing cost |
|
APR |
Helps understand overall annualised cost |
|
Processing fee |
Adds to initial borrowing cost |
|
GST/applicable taxes |
May apply to fees |
|
Tenure |
Affects EMI and total interest |
|
Foreclosure charges |
Important if closing early |
|
EMI |
Must fit your monthly budget |
|
Lender details |
Helps verify who is providing the loan |
If an offer is marketed as an instant debt consolidation loan, remember that instant processing does not mean guaranteed approval. Eligibility and approval remain subject to the lender's criteria.
Debt Consolidation vs Multiple Loans
|
Factor |
Multiple Loans |
Consolidated Loan |
|
Payments |
Multiple |
One repayment |
|
Due dates |
Several |
One |
|
Tracking |
More difficult |
Simpler |
|
Interest |
Different rates |
Based on new loan |
|
Tenure |
Different |
Usually one tenure |
|
Risk |
Missed payments possible |
Easier to track |
Consolidation can simplify cash-flow management, but borrowers should still calculate whether the new arrangement makes financial sense.
When Can Debt Consolidation Make Sense?
A consolidation strategy may be worth exploring when:
-
You have several repayments to manage.
-
Existing borrowing has a relatively high cost.
-
You qualify for a suitable new loan.
-
Your income can comfortably support the new EMI.
-
You want to simplify repayment dates.
-
You have a clear plan to avoid accumulating fresh debt.
Avoid These 5 Mistakes
-
Borrowing more than required.
-
Looking only at EMI.
-
Ignoring processing fees.
-
Continuing unnecessary credit-card spending.
-
Taking another loan immediately after consolidation.
Pocketly: Instant Personal Loans for Short-Term Financial Needs
Not every borrower looking for debt relief needs a large, long-tenure consolidation loan.
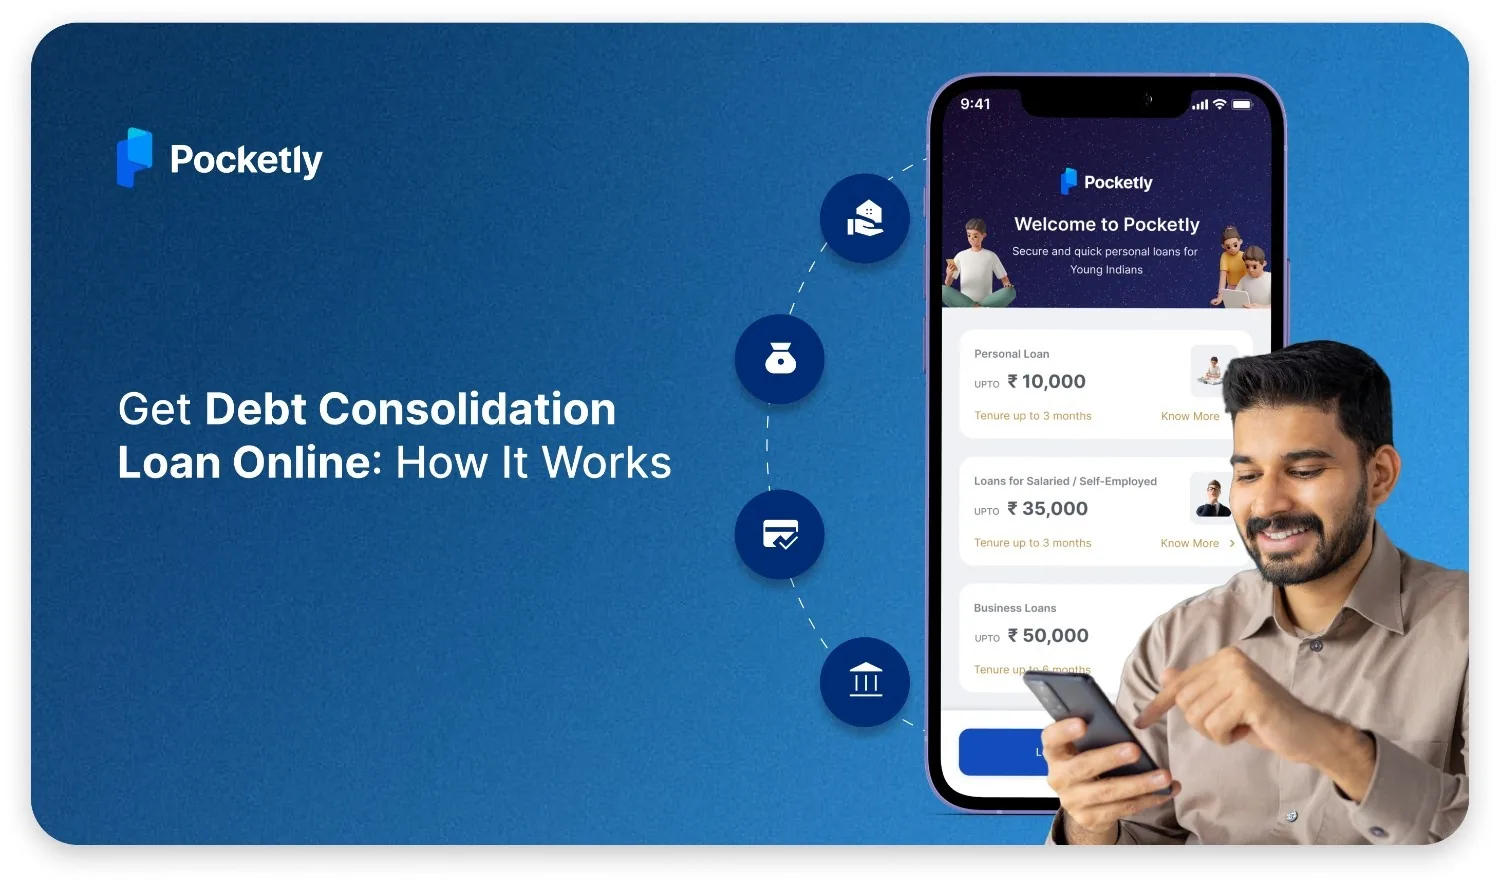
For smaller financial requirements, Pocketly provides a 100% digital personal-loan journey with loans ranging from ₹1,000 to ₹50,000, subject to eligibility and applicable terms. Pocketly's supplied product information states that approval can be received in a maximum of 7 minutes.
Pocketly is designed for India's young borrowers, including students, first-jobbers, salaried professionals, freelancers and self-employed individuals. Its supplied materials highlight fast disbursal, flexible repayment and digital processing.
Pocketly also states that no CIBIL score is required for applying through its platform, subject to its applicable eligibility and lending criteria.
According to the supplied Pocketly information, the platform has 10M+ users/app downloads and has facilitated more than ₹3,000 crore in credit.
For borrowers considering Pocketly, the currently supplied disclosures show:
|
Loan Detail |
Pocketly |
|
Loan amount |
₹1,000–₹50,000 |
|
Repayment period |
61 days–9 months |
|
Interest rate |
2%–3% per month |
|
Processing fee |
0%–7.5% + applicable GST |
|
APR |
30%–121% |
|
Foreclosure charge |
2.5% of principal outstanding |
Always review your personalised offer, Key Facts Statement, fees, repayment schedule and total repayment before accepting a loan.
Pocketly's responsible-lending information states that Speel Finance Company Private Ltd. is an RBI-registered NBFC and that Pocketly operates as its technology platform. It also states that borrowing costs, fees and lending terms are disclosed to borrowers.
Final Takeaway
A debt consolidation loan can simplify multiple repayments, but the smartest approach is to look beyond the EMI.
Before borrowing, calculate your outstanding debt, compare APR and fees, understand the tenure and make sure the new repayment fits comfortably within your monthly budget.
If your requirement is smaller and short-term, Pocketly offers instant personal loans up to ₹50,000, a digital application process and fast approval for eligible borrowers.
Need funds without lengthy paperwork? Explore Pocketly's personal-loan options and check your eligibility today.
FAQs
1. What is a debt consolidation loan?
It is a new loan used to repay multiple existing debts so the borrower can manage a single repayment arrangement.
2. How can I get a debt consolidation loan?
Calculate your existing debt, compare suitable lenders, check eligibility and costs, and apply only after reviewing the complete repayment terms.
3. Are debt consolidation loans available online?
Yes, some lenders offer digital personal-loan applications that borrowers can complete online, subject to eligibility.
4. Are instant debt consolidation loans guaranteed?
No. Faster processing does not mean guaranteed approval. Approval depends on lender-specific eligibility and assessment.
5. Can a personal loan be used for debt consolidation?
A personal loan may be used for debt consolidation where permitted by the lender and appropriate to the borrower's financial situation.
6. Does debt consolidation reduce EMI?
It can, but a lower EMI may result from a longer tenure. Always compare total repayment.
7. Is debt consolidation always cheaper?
No. Fees, interest, tenure and foreclosure charges can change the overall cost.
8. Can self-employed people apply for personal loans?
Eligibility depends on the lender. Pocketly provides personal-loan options for eligible self-employed borrowers.